Key Takeaways
- Canada’s OSFI says tokenized deposits remain traditional bank deposits, meaning blockchain does not create a new legal category.
- Federally regulated banks can explore tokenized deposits within the existing banking framework instead of waiting for a separate crypto rulebook.
- The guidance does not remove oversight, with banks still subject to existing capital, cybersecurity, technology, and supervisory requirements.
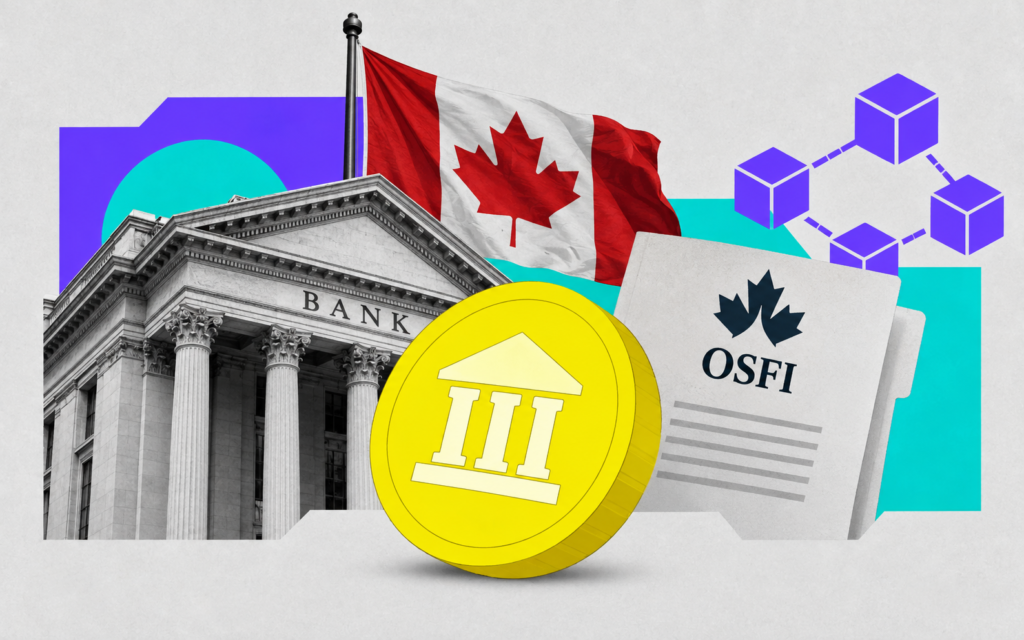
Canada’s banking regulator has clarified that tokenized bank deposits do not need to be treated as a new class of financial product simply because they operate using blockchain or other digital infrastructure.
The Office of the Superintendent of Financial Institutions said on Sept. 10 that the underlying technology used to deliver a financial product does not determine its legal nature.
In practical terms, OSFI said that tokenized deposits are not legally distinct from traditional bank deposits, providing federally regulated financial institutions with greater clarity as they explore blockchain-based banking products.
The position could remove one of the regulatory questions facing Canadian banks considering tokenized money. Rather than creating a separate legal category specifically for deposits represented on distributed ledgers, OSFI is taking what it calls a technology-neutral approach.
Tokenized Deposits Remain Bank Deposits
Under the regulator’s interpretation, the key question is what the financial product actually represents, rather than whether the underlying records are maintained on a blockchain.
That distinction separates tokenized deposits from crypto assets such as stablecoins issued by non-bank entities.
A tokenized bank deposit remains a claim on a regulated financial institution, while the digital token effectively changes how that claim can be represented, transferred, or integrated with other financial infrastructure.
The Bank of Canada has similarly described tokenization as the process of representing traditional assets and their ownership records on a digital ledger. Its research notes that tokenized systems could potentially offer faster settlement and reduce counterparty risks, although the design and legal structure of individual systems remain important.
Banks Still Face Existing Regulatory Requirements
OSFI’s clarification does not mean banks can launch blockchain products without oversight.
Financial institutions remain responsible for ensuring that tokenized products comply with existing federal laws and regulatory requirements.
OSFI specifically pointed to its technology and cyber-risk framework, as well as rules governing risks created by third-party service providers.
Banks are also expected to consult their OSFI supervisors before launching novel products or services.
That makes the announcement less of a deregulation move and more of a clarification that existing banking rules can continue to apply even when the underlying infrastructure changes.
Canada Takes a Technology-Neutral Route
The clarification arrives as OSFI is separately updating its framework for banks with crypto-asset exposure.
On Sept. 10, the regulator also published its final 2027 capital and liquidity rules for crypto assets. Those rules, based partly on Basel Committee standards, determine how banks must account for risks associated with different crypto exposures.
The framework is scheduled to take effect in November 2026 or January 2027, depending on an institution’s fiscal year.
The two developments point to a broader regulatory approach in Canada: traditional financial products do not necessarily become “crypto” products simply because they are moved onto blockchain infrastructure.
For banks experimenting with programmable payments, tokenized cash, or blockchain settlement, that distinction could be significant.
Top Trending Crypto Articles
The information provided in this article is for informational purposes only. It is not intended to be, nor should it be construed as, financial advice. We do not make any warranties regarding the completeness, reliability, or accuracy of this information. All investments involve risk, and past performance does not guarantee future results. We recommend consulting a financial advisor before making any investment decisions.

Giuseppe Ciccomascolo began his career as an investigative journalist in Italy, where he contributed to both local and national newspapers, focusing on various financial sectors.
Upon relocating to London, he worked as an analyst for Fitch's CapitalStructure and later as a Senior Reporter for Alliance News. In 2017, Giuseppe transitioned to covering cryptocurrency-related news, producing documentaries and articles on Bitcoin and other emerging digital currencies. He also played a pivotal role in establishing the academy for a cryptocurrency exchange website. Crypto remained his primary area of interest throughout his tenure as a writer for ThirdFloor.