Where do we expect the eurozone interest rates to be in five years? | Credit: Ralph Orlowski/Getty Images
Share
Key Takeaways
The European Central Bank raised its interest rates in September.
This marks the second rate increase after the June one, which was the first in almost three years.
The next monetary policy decision is scheduled for Oct. 29, 2026.
The European Central Bank (ECB) raised interest rates again on Sept. 10, delivering its second 25-basis-point increase in three months as the Middle East conflict continued to drive energy prices and inflation higher.
The decision confirmed Rabobank strategist Bas van Geffen’s earlier prediction that the ECB would follow June’s increase with another hike in September.
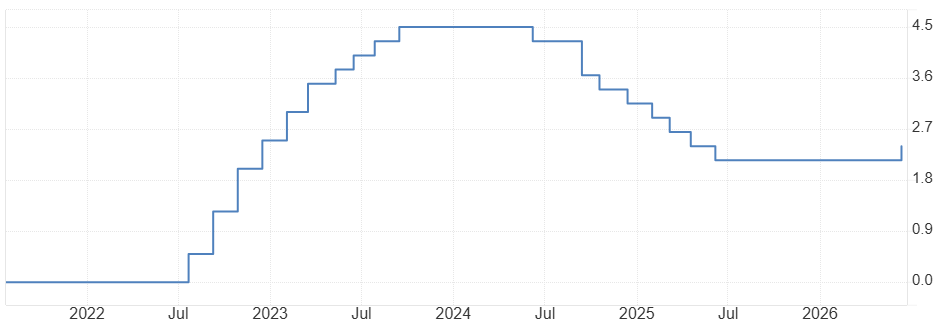
The ECB increased all three key interest rates by 25 basis points. From Sept. 16, the deposit facility rate will rise to 2.50%, the main refinancing rate to 2.65% and the marginal lending rate to 2.90%.
Policymakers said inflation will remain “well above target for an extended period,” with the Middle East conflict pushing energy costs higher and threatening broader price pressures.
The Governing Council decided to raise interest rates by 0.25 percentage points.
Inflation is set to remain well above target for an extended period, says President @Lagarde. We are committed to ensuring that inflation stabilises at 2%.
Eurozone inflation accelerated to 3.3% in August from 2.9% in July, while energy inflation climbed to 14.3% from 10.3%. Inflation excluding energy and food eased slightly to 2.4%.
“The conflict in the Middle East continues to generate inflation pressures,” the ECB said.
“Today’s decision underscores the Governing Council’s commitment to setting monetary policy to ensure that inflation stabilises at its 2% target in the medium term.”
The ECB now expects headline inflation to average 3.0% in 2026, 2.5% in 2027 and 2.1% in 2028. Compared with its June projections, it left the 2026 estimate unchanged but raised its forecasts for the following two years.
Core inflation will average 2.5% in 2026, 2.6% in 2027 and 2.3% in 2028, according to the new projections.
Will the ECB Raise Rates Again?
The ECB gave no commitment on its next move, maintaining its data-dependent, meeting-by-meeting approach.
President Christine Lagarde said policymakers will monitor how persistently higher energy prices affect wages, inflation expectations and broader pricing behavior.
The central bank expects inflation to remain above target through the first half of 2027 before returning to around 2% toward the end of that year.
The risk of another increase remains. Prolonged disruption to oil or gas supplies, low gas-storage levels or a cold winter could intensify inflation and force the ECB to tighten policy further.
Still, the Governing Council stressed that it had not committed to a predetermined rate path. Future decisions will depend on incoming economic data, underlying inflation and the effectiveness of monetary-policy transmission.
Introducing the European Central Bank
The European Central Bank (ECB) is a central component of the Eurosystem and the European System of Central Banks (ESCB), making it one of the seven institutions of the European Union (EU). As one of the world’s foremost central banks, it holds a position of immense significance on the global stage.
The ECB Governing Council formulates monetary policy for the Eurozone and the European Union. It manages the foreign exchange reserves of EU member states, conducts foreign exchange operations, and defines the intermediate monetary objectives and key interest rates within the EU.
To execute these policies and decisions, the ECB Executive Board operates under the authority of the Governing Council and may issue directives to the national central banks as needed. Additionally, the ECB possesses the exclusive authority to authorize the issuance of euro banknotes. Meanwhile, member states’ issuance of euro coins requires prior approval from the ECB. The ECB also oversees the functioning of the TARGET2 payments system.
Established in May 1999 through the Treaty of Amsterdam, the ECB’s crucial mission is to ensure and preserve price stability. Subsequently, on Dec. 1, 2009, the Treaty of Lisbon came into effect, officially designating the ECB as an EU institution.
Eurozone Expansion
Initially, the ECB was established to serve the Eurozone, consisting of eleven member countries. Over time, the Eurozone expanded to include Greece in Jan. 2001. It also added Slovenia in Jan. 2007, Cyprus, and Malta in Jan. 2008. Furthermore, Slovakia in Jan. 2009, Estonia in Jan. 2011, Latvia in Jan. 2014, Lithuania in Jan. 2015, and Croatia in Jan. 2023.
Currently, President Christine Lagarde leads the ECB, which has its headquarters in Frankfurt, Germany. Before its new headquarters, it operated from the Eurotower.
The ECB operates in direct accordance with European Union law. Its €11 billion capital stock is collectively owned by all 27 central banks of EU member states as shareholders. Based on the population and GDP of member states, the initial capital allocation key was established in 1998 but has since undergone adjustments. Notably, shares within the ECB are non-transferable and cannot serve as collateral.
ECB Interest Rates
The key interest rates are instrumental tools the ECB uses within its operational framework to preserve price stability within the euro area.
These rates hold significant importance in conducting monetary policy, as they directly impact the cost of borrowing for various economic entities. These include governments, businesses, and households, both in capital markets and the market for bank loans. Furthermore, they influence the returns on various saving instruments, such as bank deposits.
Consequently, the ECB’s monetary policy decisions have a far-reaching impact on households’ and businesses’ spending, saving, and investment choices. It ultimately affects overall economic activity and, in turn, inflation rates.
ECB establishes this rate to provide the banking system with weekly liquidity injections. It determines the cost credit institutions incur when borrowing funds from the ECB for one week.
Deposit Facility Rate
The ECB also sets the rate for the deposit facility. This dictates the interest paid to credit institutions for overnight deposits held at the central bank. Notably, the deposit facility rate remained negative from 2014 until July 2022.
Marginal Lending Facility Rate
This rate represents the cost credit institutions bear when they borrow money overnight from the ECB.
These interest rates are pivotal in the ECB’s pursuit of its monetary policy objectives. They significantly influence the broader economic landscape and inflation dynamics.
Eurozone Interest Rate Projections for the Next 5 Years
Given the many current uncertainties, formulating a realistic forecast for ECB interest rates over the next five years presents a considerable challenge. Nevertheless, the European Central Bank itself has offered projections extending as far as 2025 in its survey of professional forecasters.
According to their ECB interest rate predictions, they foresaw a rise to 3% in Q1 2023, a figure already materialized. They also predicted a further increase to 3.5% in Q2. A gradual decrease below 3% in 2024 and 2025 would follow.
In contrast, ING’s March policy rate forecasts suggested the ECB interest rate would climb to 3.5% in Q1 2023. It would reach 4% in Q2, maintaining this level until early 2024. Their analysts expected a rate of 3.5% in late 2024, gradually declining to 3% in late 2025.
Based on their econometric models, trading Economics anticipated a decrease to 2.75% in 2024 and a further decline to 1.5% in 2025.
The Influence of Interest Rates on Cryptocurrency
Cryptocurrencies, Bitcoin included, have demonstrated remarkable resilience even in the face of rising interest rates. Notably, Bitcoin experienced significant growth, with a surge of 2,000% observed between 2015 and 2016.
However, it is crucial to recognize that elevated interest rates can produce diverse effects on the cryptocurrency market. Some experts argue that persistently high inflation, rising gas prices, and increased energy costs linked to higher interest rates may potentially reduce risk appetite, thus creating challenges for cryptocurrencies.
Central Banks and Their Impact on Cryptocurrencies
Central banks have a significant influence on shaping economic conditions, directly impacting money circulation and financial market stability. Their ability to adjust interest rates directly affects borrowing rates for financial and banking institutions.
In response to widespread inflation, major central banks in developed economies, such as the Fed, the ECB, and the BoE, have chosen to raise interest rates.
It is worth noting the increasingly intertwined relationship between cryptocurrencies and these macroeconomic and monetary shifts. The decisions to raise interest rates, particularly by the Fed, have immediate repercussions for cryptocurrency markets.
The Federal Reserve’s more assertive stance has injected uncertainty into the cryptocurrency space, affecting market sentiment as tighter monetary policies take hold.
Disclaimer:
The information provided in this article is for informational purposes only. It is not intended to be, nor should it be construed as, financial advice. We do not make any warranties regarding the completeness, reliability, or accuracy of this information. All investments involve risk, and past performance does not guarantee future results. We recommend consulting a financial advisor before making any investment decisions.
Giuseppe Ciccomascolo began his career as an investigative journalist in Italy, where he contributed to both local and national newspapers, focusing on various financial sectors.
Upon relocating to London, he worked as an analyst for Fitch's CapitalStructure and later as a Senior Reporter for Alliance News. In 2017, Giuseppe transitioned to covering cryptocurrency-related news, producing documentaries and articles on Bitcoin and other emerging digital currencies. He also played a pivotal role in establishing the academy for a cryptocurrency exchange website. Crypto remained his primary area of interest throughout his tenure as a writer for ThirdFloor.