Where do we expect the US Interest rates to be in five years?
Share
Key Takeaways
The Federal Reserve raised its interest rates in September.
The US central bank hiked the rates for the first time in three years.
Warsh & Co. also issue new projections for the next policy moves and the US economy.
The next Federal Open Market Committee meeting will be on Oct. 27-28.
The Federal Reserve raised its benchmark interest rate by 25 basis points in September, ending a months-long pause as policymakers moved to counter persistent inflation.
After a two-day meeting, the Federal Open Market Committee voted unanimously, 12-0, to lift the federal funds target range to 3.75%-4.00%. It marked the Fed’s first rate increase in three years and followed five consecutive meetings in which policymakers had left rates unchanged.
The unanimous decision also marked a sharp contrast with July, when the FOMC voted 9-3 to keep rates unchanged amid disagreements over how aggressively the central bank should respond to inflation.
Try Our Recommended Crypto Exchanges
Sponsored
Disclosure
We sometimes use affiliate links in our content, when clicking on those we might receive a commission at no extra cost to you. By using this website you agree to our terms and conditions and privacy policy.
The Fed said economic activity continued to expand at a “solid pace,” supported by resilient domestic spending, strong productivity growth and robust capital investment.
However, officials warned that inflation remained elevated and said the September rate increase would support a “timelier” return to the central bank’s 2% target.
The median FOMC projection now puts the federal funds rate at 4.1% at the end of both 2026 and 2027, compared with June projections of 3.8% and 3.6%, respectively. The median then falls only gradually to 3.9% in 2028 and 3.6% in 2029.
The dot plot therefore implies another 25-basis-point hike before the end of 2026 and no rate cuts in 2027.
🚨 THE FED’S DOT PLOT JUST SENT A HUGE MESSAGE TO THE BOND MARKET.
The Fed hiked rates today to 3.75%–4.00%.
Its new projections point to ANOTHER hike by year-end, then no cuts in 2027.
The median projected rate stays around 4.1% through the end of next year.
Among the 18 officials submitting 2026 projections, 12 placed the appropriate year-end rate at 4.125%, while four projected 4.375%. Only two saw rates ending the year around the current midpoint of 3.875%. For 2027, eight officials projected 4.375% and another six expected 4.125%, underscoring the Fed’s higher-for-longer stance.
The shift is substantial. In June, the median projection had pointed to lower rates in 2027, while the September projections now suggest policymakers expect restrictive monetary conditions to persist considerably longer.
The dot plot is not a binding commitment, however. Each dot represents an individual FOMC participant’s assessment of appropriate monetary policy based on the economic outlook at the time, meaning the projected path can change as new data emerge.
Warsh and Fed Face Persistent Inflation
Fed Chair Kevin Warsh has repeatedly stressed the central bank’s commitment to returning inflation to its 2% target, and the latest projections show price pressures remaining elevated in the near term.
The Fed now expects headline PCE inflation to reach 3.7% in 2026, slightly above the 3.6% projected in June. Core PCE inflation is forecast at 3.4%, up from the previous 3.3% estimate. Policymakers expect headline inflation to fall to 2.3% in 2027 and 2.1% in 2028 before reaching 2% in 2029.
At the same time, officials became more optimistic about economic growth. Median real GDP growth is now projected at 2.3% in 2026 and 2.4% in 2027, while the unemployment rate is expected to remain at 4.1% through 2029.
Fed Chair Kevin Warsh announces a rate hike for the first time in three years from 3.75%-4%: "The FOMC decided to raise the target range for the federal funds rate by a quarter of a percentage point." pic.twitter.com/HNzd2H6XWf
That combination of stronger growth, lower projected unemployment and inflation remaining above target, helps explain why policymakers now see less scope to reduce borrowing costs.
Higher interest rates are designed to restrain demand and inflation by increasing the cost of credit for households and businesses. They also have broad implications for financial markets, affecting mortgages, car loans, corporate financing, Treasury yields and risk assets such as Bitcoin.
The September projections therefore suggest the Fed’s tifedghtening cycle may not be finished. Rather than preparing for rate cuts next year, most policymakers currently see rates remaining around 4.1% through the end of 2027, making the evolution of inflation and economic growth central to the Fed’s next moves.
Energy Prices and Inflation Outlook Remain Key Variables
A major driver behind the Fed’s hawkish outlook is the recent resurgence in energy-driven inflation. Rising oil prices have pushed headline inflation higher, complicating the central bank’s efforts to guide inflation back toward its long-term target.
However, the inflation outlook remains highly dependent on developments in global energy markets.
Recent diplomatic efforts aimed at stabilizing supply conditions in the Middle East could ease pressure on oil prices in the coming months, potentially reducing one of the most significant contributors to recent inflation gains.
If energy costs begin to normalize, policymakers may gain greater confidence that inflation is moving back toward target levels, reducing the need for additional rate hikes. Conversely, any renewed supply disruptions or commodity price spikes could reinforce the Fed’s higher-for-longer stance.
For now, the June meeting reinforced a clear message: while interest rates remain unchanged, the Federal Reserve is not yet ready to pivot toward easing.
Under Kevin Warsh’s leadership, policymakers appear determined to maintain flexibility while closely monitoring inflation risks, even as concerns about slower economic growth continue to mount.
The coming months will determine whether inflation moderates enough to justify a softer policy stance or whether the Fed’s increasingly hawkish projections become reality. Either way, the June meeting highlighted that the battle against inflation remains far from over.
Interest Rates Impact on Financial Markets
Projections and decisions regarding interest rates hold immense sway over the broader economy. They affect various financial markets, including equities, bonds, and commodities.
The Fed’s key tool in this regard is the Federal Funds Rate (FFR). This is the base interest rate that influences banks, bond markets, and the economy. The Fed makes these rate decisions during its FOMC meetings, held eight times yearly. The rate adjustments in 2022 brought about several hikes, with more in store for 2023.
The increase in FFR, in turn, leads to a rise in the prime rate, the fundamental interest rate charged by banks to creditworthy customers. If the FFR goes up, so does the cost of loans and mortgages. This uptick in the cost of servicing loans translates to reduced discretionary income for consumers and businesses. This, in turn, can dampen overall demand and mitigate inflationary pressures.
Federal Reserve’s fund rates decreased during weak economic periods.
The implications for stocks are twofold: consumer-dependent sectors like retail and hospitality may face headwinds due to reduced consumer spending. Growth stocks that rely on capital and borrowing could also suffer. This is as investors shift their focus toward more stable, value-oriented investments in response to market volatility and potential downturns.
Pressure On Bonds
From a mechanical perspective, rising interest rates put downward pressure on bond values. As rates climb, the bond yield becomes less attractive than the prevailing base rate, leading to a sell-off in bonds.
This effect is particularly pronounced in the case of long-term bonds. In this case, the discrepancy between their yield and the base rate grows over time.
As a result, fixed-income securities also lose value as the opportunity cost of not owning interest-rate-tracking assets increases. Thus, predicting interest rates over the next five years becomes a critical indicator of market trends.
Historical Perspective on Interest Rate Policy
The U.S. has experienced periods of both high and low interest rate volatility in its history. In the postwar era of the 1950s, the FFR remained below 2%, bolstered by postwar stimulus and income growth. Over the next two decades, the rate fluctuated between 3% and 10% during the 1960s and 1970s, soaring to a record high of 19.1% in 1980 amid rampant inflation.
As the U.S. economy stabilized and inflation was controlled, the FFR hovered around 5% throughout the 1990s. However, recessions in 2001 and 2008 forced rates down to historically low levels, where they remained until 2016.
The COVID-19 pandemic necessitated another significant rate cut, nearly to zero. In 2022, the Fed increased rates seven times, followed by three hikes in 2023. The central bank brought the rate to its current range between 5.25% and 5.50%, the highest level in 16 years.
Factors Influencing Future Interest Rates
The Fed now faces the challenge of navigating uncertain economic conditions. These are marked by rising prices and an economic slowdown compounded by supply chain disruptions. Inflation, as well as the potential for a recession, is a top concern.
High Inflation
Inflation has been a focal point for central bank action. In 2022 and 2023, inflation accelerated due to a mix of demand and supply factors, sometimes interconnected. The Fed’s more hawkish stance appeared to have contributed to moderate price increases.
The rhetoric shifted in July. Official data from the U.S. Labor Department revealed that the inflation rate had reached 3.2% year over year. Costs of housing, car insurance, and food drove this increase.
This marked an uptick from June, which had seen the lowest rate over two years, at 3%. Analysts had anticipated this rise in the headline rate, considering the relatively weak price inflation observed in the previous July.
U.S. consumer price inflation peaks and lows
US Dollar Resilience
Despite economic turbulence, the U.S. dollar has remained remarkably resilient. Its status as a safe-haven currency, coupled with increased investor appeal due to the Fed’s hawkish monetary policy, has bolstered its performance. However, as the Fed’s monetary tightening slows and potentially pauses, the strength of the U.S. dollar appears to be waning.
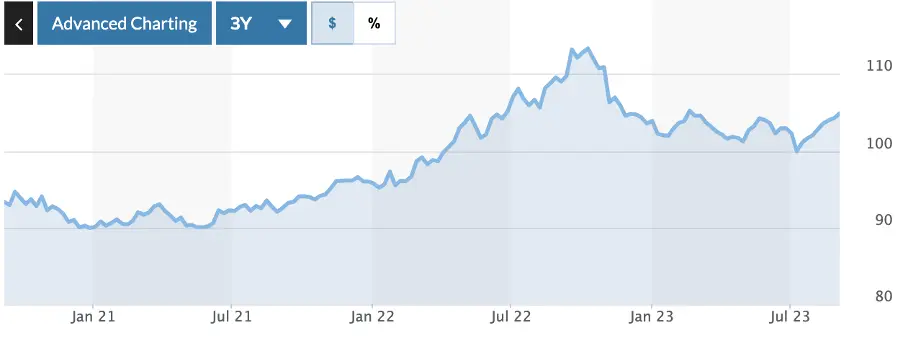
USD performance.
Projected Interest Rates in the Next Five Years
The Federal Reserve’s latest projections offer a glimpse into how U.S. interest rates may evolve through the end of the decade. While policymakers left rates unchanged at 3.5%-3.75% during the June 2026 Federal Open Market Committee (FOMC) meeting, updated forecasts suggest that the era of ultra-low borrowing costs remains firmly in the past.
The central bank’s outlook reflects a delicate balancing act between controlling inflation, supporting economic growth, and maintaining financial stability. Although future rate decisions remain data-dependent, current projections indicate that rates are likely to remain elevated relative to the pre-pandemic period, even if inflation gradually returns toward the Fed’s long-term target.
The Near-Term Outlook: Rates Likely to Stay Higher for Longer
The most immediate takeaway from the Fed’s latest projections is that policymakers are not yet ready to pivot toward aggressive rate cuts. According to the June 2026 Summary of Economic Projections, nine of eighteen policymakers expect at least one rate increase before the end of the year, while only one official anticipates a rate cut.
This reflects ongoing concerns about inflation, which remains above the Federal Reserve’s 2% target. Energy prices, wage growth, and resilient consumer spending continue to create upside risks for inflation, prompting officials to maintain a cautious stance.
As a result, most economists expect the federal funds rate to remain near current levels through much of 2026, with any policy easing likely to be gradual rather than dramatic.
Rates May Gradually Decline Through 2027-2029
Beyond the next year, many forecasts anticipate a slow normalization process. Historically, once inflation is under control, the Fed tends to lower rates toward a so-called “neutral rate”—the level that neither stimulates nor restricts economic activity.
Federal Reserve estimates currently place the long-run neutral federal funds rate around 3%, significantly higher than the near-zero levels that prevailed throughout much of the 2010s. This suggests that even if inflation moderates and economic growth slows, rates may settle in a range between 2.75% and 3.25% rather than returning to the extraordinarily accommodative policies seen after the Global Financial Crisis.
Several structural factors support this higher-rate environment. Persistent government deficits, increased infrastructure spending, deglobalization trends, and aging demographics may all contribute to higher baseline inflation pressures than policymakers faced in previous decades.
Consequently, investors and businesses are increasingly adjusting to the possibility that borrowing costs over the next five years will remain materially higher than those experienced during the 2010-2021 period.
How Do Interest Rates Affect Crypto?
Bitcoin and other digital assets have demonstrated resilience in a rising interest rate environment. For instance, Bitcoin experienced remarkable growth of 2,000% in 2015 and 2016, during a period marked by rising interest rates.
Nevertheless, some experts argue that persistently high inflation, gas prices, and energy costs resulting from elevated interest rates may dampen risk appetite, potentially posing headwinds for cryptocurrencies.
Central Banks and Connection With Cryptocurrencies
Central banks wield significant influence, directly affecting money circulation and financial market stability. They have the power to modify interest rates, which, in turn, affects the borrowing rates for financial and banking institutions. Recently, central banks in major developed economies, such as the Fed, ECB, and BoE, have increased interest rates in response to widespread inflation.
Notably, cryptocurrencies are increasingly intertwined with these macroeconomic and monetary shifts. In particular, the decisions to raise interest rates, especially by the Fed, directly affect the cryptocurrency markets.
In simpler terms, the Fed’s more assertive stance has cast a shadow over cryptocurrencies, impacting market sentiment as tighter monetary policies loom.
Disclaimer:
The information provided in this article is for informational purposes only. It is not intended to be, nor should it be construed as, financial advice. We do not make any warranties regarding the completeness, reliability, or accuracy of this information. All investments involve risk, and past performance does not guarantee future results. We recommend consulting a financial advisor before making any investment decisions.
Giuseppe Ciccomascolo began his career as an investigative journalist in Italy, where he contributed to both local and national newspapers, focusing on various financial sectors.
Upon relocating to London, he worked as an analyst for Fitch's CapitalStructure and later as a Senior Reporter for Alliance News. In 2017, Giuseppe transitioned to covering cryptocurrency-related news, producing documentaries and articles on Bitcoin and other emerging digital currencies. He also played a pivotal role in establishing the academy for a cryptocurrency exchange website. Crypto remained his primary area of interest throughout his tenure as a writer for ThirdFloor.