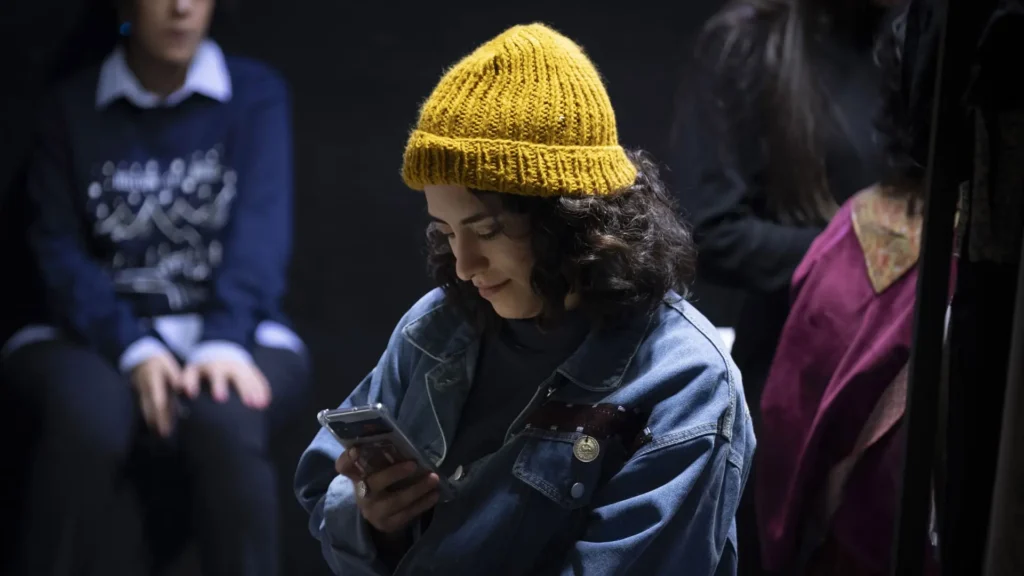
Is wealth heading towards Gen Z? | Source: Morteza Nikoubazl/NurPhoto via Getty Images.
Share
Key Takeaways
Stablecoin transaction volumes could reach $1.5 quadrillion by 2035, says Chainalysis.
Younger crypto-native generations are showing higher trust in digital assets.
Clearer U.S. stablecoin rules may boost institutional adoption.
Stablecoins could process as much as $1.5 quadrillion in annual transaction volume by 2035, driven in part by a historic shift of wealth to younger, crypto-native generations, according to a new report by blockchain analytics firm Chainalysis.
The projection, which would exceed today’s global cross-border payments market, comes amid growing regulatory momentum in the United States, raising questions about the opportunity and disruption stablecoins may bring.
Sponsored
Disclosure
We sometimes use affiliate links in our content, when clicking on those we might receive a commission at no extra cost to you. By using this website you agree to our terms and conditions and privacy policy.
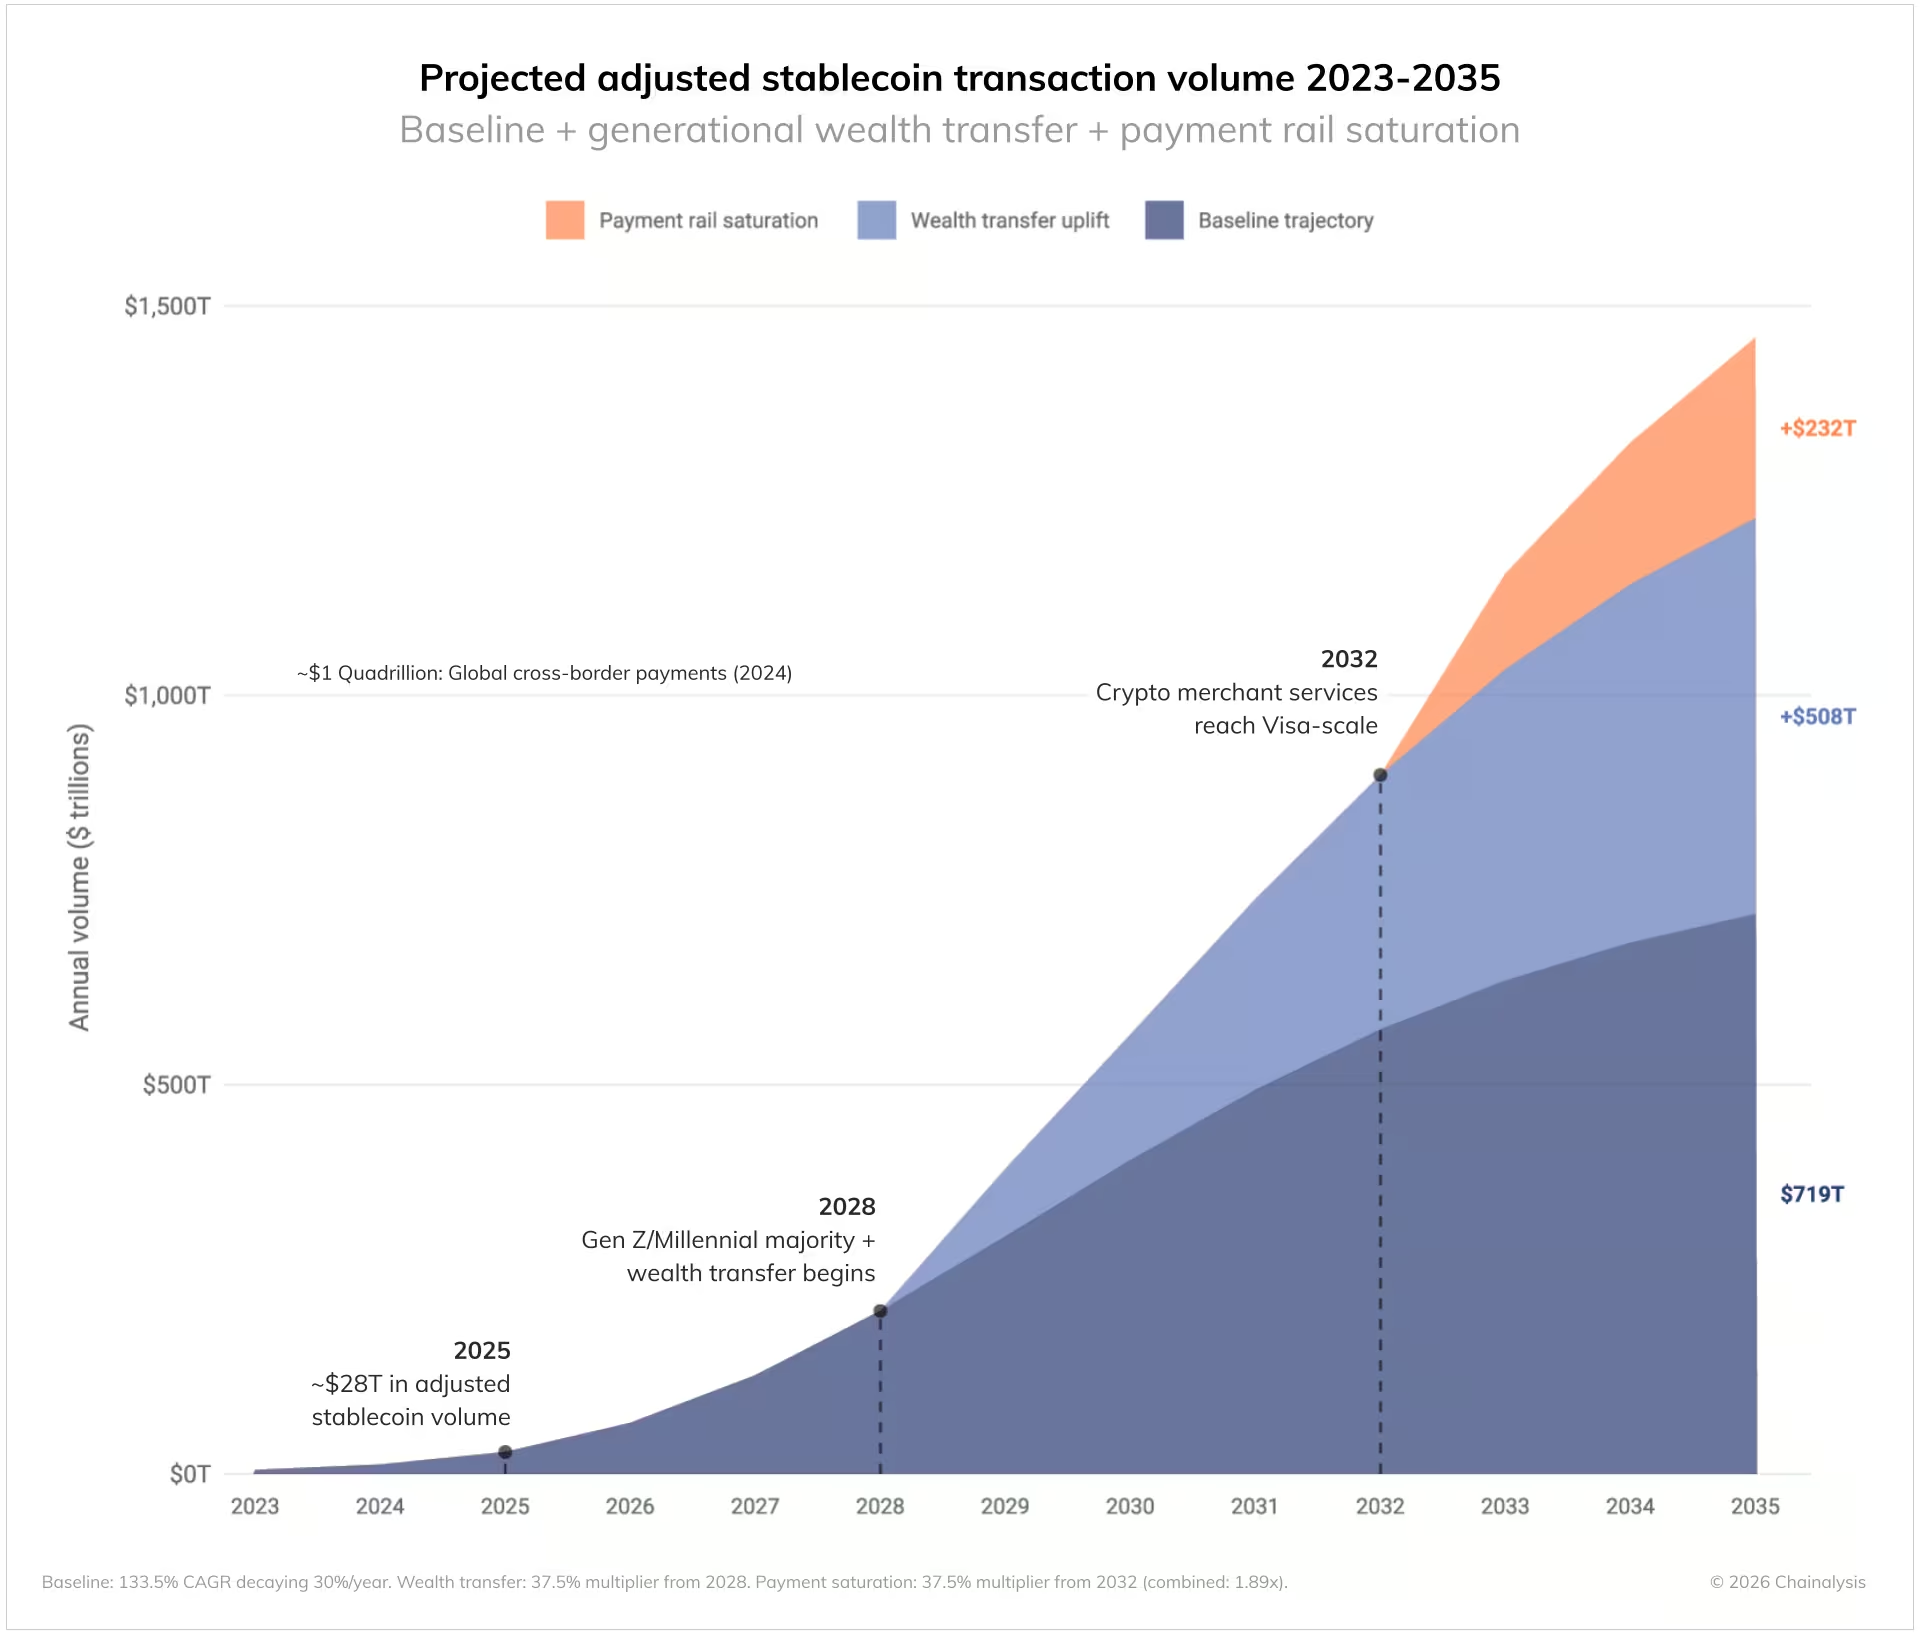
Chainalysis said stablecoins processed roughly $28 trillion in “real economic” transaction volume in 2025, after adjusting for non-economic activity such as automated trading and internal transfers.
That figure has grown at a compound annual rate of 133% since 2023. If current growth trends persist, volumes could reach $719 trillion by 2035.
However, the firm said two major structural shifts could push that figure closer to $1.5 quadrillion — most notably the transfer of up to $100 trillion in wealth from older generations to Millennials and Gen Z.
$80-100 trillion will shift over the coming decades from Boomers to Millennials and Gen Z, Chainalysis said. | Source: Chainalysis
“These younger cohorts are significantly more comfortable with digital assets,” the report said, citing survey data showing nearly half have held or currently hold crypto.
Chainalysis estimates that the generational wealth transfer alone could drive annual stablecoin transaction volume to more than $500 trillion by 2035, reshaping how capital flows through the financial system.
Adoption Surge
Beyond demographics, the report highlights payments as the clearest current use case for stablecoins, particularly in remittances and business-to-business transactions.
Unlike traditional payment systems, which rely on intermediaries, stablecoins enable near-instant transfers and operate around the clock.
This efficiency is already attracting institutional interest, with firms exploring how programmable money can be embedded directly into financial workflows.
Chainalysis argued that as adoption expands, stablecoins could move from a niche payment option to a default infrastructure layer/
The report identifies point-of-sale (POS) integration as another major catalyst.
As more merchants accept stablecoins, consumers may increasingly transact using blockchain rails without actively choosing to do so — mirroring the rise of card payments over cash.
If current trends hold, on-chain transaction volumes could rival those of Visa and Mastercard between 2031 and 2039, Chainalysis said.
Traditional Stablecoin Pressure
The rapid growth of stablecoins is prompting a strategic shift among financial institutions, which are increasingly moving from regulatory observation to active participation.
Recent industry moves — including Stripe’s acquisition of stablecoin infrastructure firm Bridge — reflect growing recognition that blockchain-based rails could underpin the next generation of payments.
“For incumbents, the calculus is becoming straightforward,” Chainalysis wrote.
Added: “The blockchain is now the essential plumbing for the next era of global payments.
Institutions that build for this reality now will help define it, while those that wait may end up settling transactions on someone else’s rails.
Stablecoin Regulatory Push
At the same time, lawmakers in the U.S. are advancing competing frameworks to regulate stablecoins, seeking to balance innovation with financial stability and consumer protection.
The proposed STABLE Act would impose stricter requirements, including limiting issuance to licensed entities, mandating full reserve backing and enforcing detailed disclosure rules. It also proposes a temporary ban on new algorithmic stablecoins.
In contrast, the GENIUS Act takes a more flexible approach, allowing smaller issuers to operate under state-level oversight while maintaining federal supervision for larger players.
Rather than curbing growth, clearer rules may accelerate institutional participation by reducing legal uncertainty, analysts say.
However, stricter compliance requirements could also raise barriers to entry for smaller issuers and reshape competitive dynamics within the sector.
In a report from State Street, the firm said: “stablecoin rules are a major step, but market structure, custody, and cross-agency coordination will continue to be where clarity is either cemented — or delayed.”
Gen Z Crypto Retirement
Separate survey data points to growing interest in crypto as part of long-term saving strategies among younger investors.
A joint survey by CryptoNinjas and Storible found that 48% of Americans said they had already included digital assets in their retirement savings, while 60% planned to increase their exposure.
Gen Z respondents showed the strongest engagement, with 58% reporting crypto allocations in retirement funds, compared with 49% of Millennials and 41% of Gen X.
Two-thirds of Gen Z participants said they intended to increase those allocations, and 76% expressed interest in crypto-focused retirement products such as Fidelity’s digital asset IRA.
However, the findings are based on a relatively small sample of 1,156 respondents and may not fully reflect broader population trends.
Broader data suggests a more nuanced picture.
While younger investors show higher ownership of crypto, they are significantly less likely to hold traditional retirement accounts.
Other studies indicate that fewer than half of Gen Z investors own crypto, while only about 11% hold retirement vehicles such as 401(k)s or IRAs.
By comparison, roughly one-third of Millennials hold both crypto and retirement accounts.
Gen Z’s Distrust Of Banks Reshaping Financial Behavior
A growing divide in how different generations view financial institutions is beginning to reshape consumer behavior, according to Roshan Robert, in an opinion piece for CCN.
“Trust in finance has stopped being inherited,” Robert wrote, pointing to survey data showing that nearly one in five Gen Z and Millennial respondents report low trust in traditional financial institutions.
He said younger generations are significantly more open to digital assets, with Gen Z and Millennials described as being five times more trusting of crypto than older cohorts.
Robert argued that this shift is often misinterpreted as speculative behavior.
“The explanation is often reduced to ‘crypto enthusiasm’ or risk-taking behavior. But that simply misses the point. The underlying causes are structural,” he said.
Robert pointed to factors such as rising student debt and declining housing affordability.
These economic pressures are changing how trust is formed, he said.
Adding: “It is no longer about what banks claim, but what they demonstrate.”
According to Robert, Gen Z places greater emphasis on transparency and control, prioritizing real-time visibility over funds, clearer fee structures and direct ownership.
“Younger consumers are not opting out of finance. Rather, they are opting out of the institutions they don’t believe serve them,” he said.
Robert also linked the trust gap to broader historical factors, including the 2008 financial crisis, which shaped younger generations’ perceptions of banks.
“Trust is not a default setting,” he said, adding that younger users continuously reassess institutions based on day-to-day interactions rather than legacy reputation.
He warned that regulatory debates, including those around stablecoins, could further widen the divide if younger consumers view restrictions as limiting access.
“For Gen Z, trust will be earned through transparency and control, not slogans and branch longevity,” Robert said.
Kurt Robson is a London-based reporter at CCN, specialising in the fast-moving worlds of crypto and emerging technology. He began his career covering local news in Cornwall after graduating from Falmouth University with First Class Honours in Journalism. There, he cut his teeth on everything from council meetings to missing swans.
He quickly rose through the ranks to become a frontline journalist at several of the UK’s leading national newspapers. Over the years, he has interviewed musicians and celebrities, reported from courtrooms and crime scenes, and secured multiple front-page exclusives.
Following the upheaval of the COVID-19 pandemic, Kurt shifted his focus to technology journalism—just ahead of the AI boom. With a natural curiosity and a trained eye for emerging trends, he has found a new rhythm in reporting on innovation.
At CCN, Kurt's work focuses on the cutting edge of crypto, blockchain, AI, and the evolving digital world. Drawing on his background in people-first reporting and his deep interest in disruptive tech, Kurt delivers stories that are insightful, entertaining, and human-centric.