BlackRock's BUIDL Nears $1 Billion Milestone on Avalanche as Real-World Asset Boom Accelerates
Share
Key Takeaways
BlackRock’s BUIDL fund tokenizes US Treasury bills, cash and repurchase agreements, allowing eligible investors to earn income through blockchain-based fund shares.
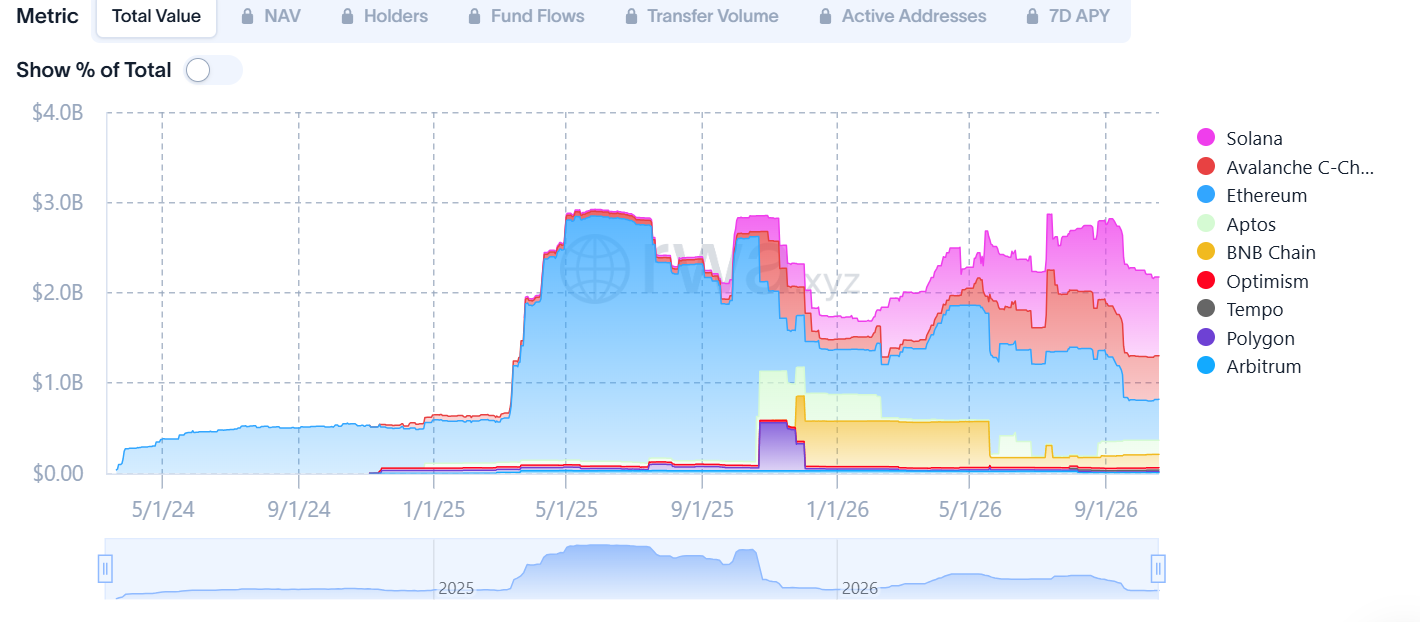
Launched in March 2024, BUIDL has grown to approximately $2.17 billion in assets as of October 2026.
BUIDL targets a stable value of $1 per token, with income accruing daily and distributed monthly. Returns are not guaranteed.
The fund operates across nine blockchain networks, including Ethereum, Solana, BNB Chain and Avalanche.
BUIDL primarily targets qualified and institutional investors, with an original minimum investment requirement of $5 million.
Binance, OKX and other platforms have integrated BUIDL into institutional collateral arrangements, expanding its use beyond traditional money market investing.
BlackRock, the world’s largest asset manager, is bringing one of Wall Street’s most familiar investment products onto blockchain networks.
Its BlackRock USD Institutional Digital Liquidity Fund, better known as BUIDL, allows eligible investors to earn returns from short-term US government securities while holding their investment as digital tokens.
Unlike Bitcoin or other cryptocurrencies, BUIDL is not designed to appreciate through price speculation. It aims to maintain a stable value of $1 per token while distributing income generated by its underlying investments.
Launched in March 2024 with tokenization company Securitize, BUIDL has grown into a multibillion-dollar product and an important example of how traditional finance is adopting blockchain infrastructure.
$BUIDL is the tokenized U.S. Treasury fund from @BlackRock.@Securitize tokenizes it, and Wormhole connects it across Ethereum, Solana, BNB Chain, Arbitrum, Avalanche, Optimism, Polygon and Aptos.
But despite its presence on public blockchains, BUIDL is not an ordinary cryptocurrency that anyone can purchase on an exchange. It remains a restricted investment product with eligibility requirements, a substantial minimum investment and risks that beginners should understand.
This guide explains how BUIDL works, where it is available, who can invest, how returns are generated and what advantages and limitations tokenized money market funds offer.
Try Our Recommended Crypto Exchanges
Sponsored
Disclosure
We sometimes use affiliate links in our content, when clicking on those we might receive a commission at no extra cost to you. By using this website you agree to our terms and conditions and privacy policy.
BUIDL is a tokenized investment fund that gives qualified investors exposure to short-term, US dollar-denominated assets.
Its official name is the BlackRock USD Institutional Digital Liquidity Fund.
The fund invests in three main categories:
US Treasury bills: Short-term debt securities issued by the US government.
Repurchase agreements: Short-term financing transactions typically secured by securities.
Cash: Funds held to support liquidity and investment operations.
BlackRock manages the underlying investment portfolio, while Securitize handles tokenization, investor records and related blockchain infrastructure. BNY Mellon serves as the fund’s custodian and administrator.
Rather than relying exclusively on traditional fund ownership records, BUIDL represents investors’ interests through blockchain-based tokens.
Each token is intended to maintain a value of $1, with investment income distributed separately.
The fund launched on Ethereum on March 20, 2024, with an initial investment minimum of $5 million.
How Does BUIDL Work?
BUIDL combines a traditional investment strategy with blockchain-based ownership and settlement.
Eligible investors subscribe to the fund through Securitize after completing identity verification and meeting the applicable investment requirements. Once approved, they receive BUIDL tokens representing their fund shares.
BlackRock invests the underlying assets in cash, US Treasury bills and repurchase agreements. These investments generate income, which is distributed to investors according to the fund’s terms.
For example, consider an eligible institution investing $5 million.
Illustrative BUIDL investment:
Initial investment: $5,000,000
Tokens received at $1 each: 5,000,000 BUIDL
Illustrative annualized yield: 3.69%
Estimated annual income: $184,500
Estimated monthly income: $15,375
The calculations assume a constant 3.69% annualized yield, based on the reported October 2026 rate. Actual returns fluctuate, and the estimates exclude any additional fees not already reflected in the quoted yield.
BUIDL’s income accrues daily and is generally distributed monthly as additional tokens. Unlike Bitcoin, investors do not need the token’s price to increase to earn a return. Instead, income comes from the fund’s underlying investments.
The blockchain records token ownership and eligible transfers, while BlackRock and its service providers continue to manage the investments, custody and other traditional fund operations.
What Is a Tokenized Money Market Fund?
A money market fund is an investment vehicle that generally holds short-term, relatively low-risk debt instruments and cash equivalents.
Investors commonly use these funds to manage cash reserves, earn income and preserve liquidity rather than pursue aggressive capital growth.
A tokenized money market fund follows a similar investment strategy but represents ownership through digital tokens recorded on a blockchain.
The difference is primarily in how ownership and transfers are managed, not necessarily in the assets generating returns.
Traditional money market fund
Tokenized money market fund
Ownership recorded through conventional financial systems
Ownership represented by blockchain tokens
Transfers depend on conventional operating arrangements
Eligible token transfers may operate around the clock
Typically accessed through banks, brokers or fund platforms
May require approved wallets and specialized platforms
Returns come from underlying financial assets
Returns also come from underlying financial assets
Subject to investment and market risks
Adds blockchain, custody and smart contract risks
Tokenization does not automatically make a fund safer or more profitable. Its potential advantage lies in improving the movement, settlement and use of existing financial assets.
How Big Is BlackRock’s BUIDL Fund in 2026?
BUIDL has grown substantially since its launch, although its assets fluctuate as institutional investors subscribe to and redeem shares.
The fund surpassed $1 billion in assets by March 2025, roughly one year after its launch. Its expansion has coincided with broader institutional interest in tokenized US Treasury products.
However, BUIDL is not the only product competing for institutional capital.
RWA.xyz’s October data places Circle’s USYC and Ondo’s USDY ahead of BUIDL by total value, illustrating how quickly the tokenized Treasury market has developed.
BlackRock USD Institutional Digital Liquidity Fund Metrics. | Source: rwa.xyz
Tokenized product
Approximate value, October 2026
Circle USYC
$2.39 billion
Ondo USDY
$2.36 billion
BlackRock BUIDL
$2.17 billion
Franklin Templeton iBENJI
$1.71 billion
These values are rounded and may change with subscriptions, redemptions and market activity.
BUIDL’s growth is significant, but the more important development may be how the fund is being used. What began primarily as an investment product is increasingly being integrated into crypto trading, collateral management and institutional settlement infrastructure.
Which Blockchains and Markets Is BUIDL Available On?
BUIDL originally launched on Ethereum but has since expanded to multiple blockchain networks.
As of October 2026, its supported networks include:
Blockchain
Expansion
Ethereum
Original launch, March 2024
Arbitrum
November 2024
Aptos
November 2024
Avalanche
November 2024
Optimism
November 2024
Polygon
November 2024
Solana
March 2025
BNB Chain
November 2025
Tempo
July 2026
The July 2026 Tempo expansion was designed to support institutional payment and treasury applications, allowing eligible participants to access tokenized yield-bearing assets within blockchain-based financial workflows.
The geographic question is different from blockchain availability.
The real crypto adoption is happening on Wall Street.
BlackRock's tokenized money-market fund, BUIDL, has grown to nearly $3 billion in under two years, holding Treasuries and cash on a blockchain. This is the plumbing of finance moving on-chain. When the largest asset manager… pic.twitter.com/H1Brhj33PT
BUIDL’s presence on nine networks does not mean investors in every country can purchase it. Access depends on investor qualifications, local securities rules, the relevant offering terms and Securitize’s onboarding requirements.
The fund is structured as a private securities offering rather than a globally available retail investment. Eligible US investors must satisfy applicable qualified purchaser and other offering requirements. Investors outside the US must also meet the relevant jurisdictional and distribution rules.
BlackRock has not established unrestricted retail availability across the US, UK, European Union, Canada or other major markets.
BUIDL is primarily designed for qualified purchasers and institutional investors rather than everyday retail investors.
Its original offering established a minimum initial investment of $5 million.
In the US, an individual generally qualifies as a qualified purchaser by owning at least $5 million in investments, subject to the applicable legal definition. Certain institutional entities can qualify under different thresholds.
Meeting a wealth threshold does not automatically guarantee acceptance into the fund.
Investors must also satisfy applicable identity verification, anti-money laundering and other compliance requirements.
Importantly, the fund’s $5 million initial subscription requirement is separate from the legal definition of a qualified purchaser.
This means that even an investor who meets the eligibility criteria may still need to satisfy the fund’s minimum subscription and any additional conditions.
How Can You Invest in BlackRock’s BUIDL Fund?
Investing in BUIDL is different from purchasing Bitcoin or an exchange-traded fund through a standard brokerage account.
Eligible investors generally follow a regulated subscription process through Securitize.
Step 1: Check investor eligibility
Determine whether you meet the applicable qualified purchaser requirements and the fund’s minimum investment conditions.
Step 2: Contact Securitize
Visit the officialSecuritize website and inquire about BUIDL subscription availability and onboarding.
Step 3: Complete compliance checks
Provide the required identification, investor qualification documents and source-of-funds information.
Step 4: Review the offering documents
Examine the fund’s fees, investment risks, redemption provisions, permitted wallets and relevant share class.
Step 5: Subscribe and receive tokens
Once approved, fund the investment through the supported subscription arrangements. The corresponding fund shares are issued as blockchain tokens to an approved wallet or custody arrangement.
Investors cannot simply connect an anonymous wallet and purchase authentic BUIDL shares without going through the required authorization process.
The official offering documents, rather than third-party websites or token listings, determine the actual investment conditions.
Can Retail Investors Buy BUIDL on Coinbase, Binance or Uniswap?
Not through the ordinary retail trading process.
BUIDL is not listed as an unrestricted retail cryptocurrency or conventional exchange-traded security.
Although Binance, Crypto.com, Deribit and OKX have announced integrations involving BUIDL, these arrangements primarily concern eligible institutional trading and collateral services.
In February 2026, BlackRock and Securitize also collaborated with Uniswap Labs to introduce trading functionality using UniswapX.
The arrangement allows approved investors to obtain quotes from whitelisted trading participants and settle transactions onchain. It does not mean anyone using Uniswap can freely purchase the fund.
Securitize remains involved in investor qualification and trading access.
Investors should be particularly cautious about unrelated tokens using the BUIDL name. A token appearing on a decentralized exchange is not proof that it represents an authorized share of BlackRock’s fund.
How Much Does BUIDL Pay in Interest?
BUIDL does not offer a fixed interest rate.
Its returns depend primarily on income generated by its holdings of Treasury bills, repurchase agreements and cash, after applicable fund expenses.
Because short-term Treasury yields are influenced by Federal Reserve monetary policy, BUIDL’s income can change as market interest rates move.
When short-term rates rise, newly purchased Treasury securities may offer higher yields. When rates fall, income from newly acquired instruments may decline.
Unlike a conventional savings account, BUIDL’s returns are investment distributions, not guaranteed bank interest.
The fund’s original structure provides for income to accrue daily and be distributed monthly through additional tokens. Investors should consult current fund documentation for the yield applicable to their share class.
A 7-day yield, where published, reflects a recent annualized income measure. It is not a guarantee that the same return will continue for a full year.
Is BUIDL a Stablecoin Like USDT or USDC?
No. Although BUIDL targets a $1 token value, it is fundamentally different from a payment stablecoin.
USDT and USDC are primarily designed to function as digital representations of the US dollar for payments, transfers and trading.
BUIDL represents an investment interest in a regulated private fund structure holding income-producing assets.
Features
BUIDL
USDT / USDC
Main purpose
Institutional investment and collateral
Payments, transfers and trading
Target value
$1 per token
$1 per token
Yield to holders
Yes, through fund distributions
Generally not from simply holding the token
Retail availability
Restricted
Broadly available, subject to jurisdiction
Transfers
Approved participants
Generally permissionless on supported networks, subject to issuer controls
Underlying legal structure
Private investment fund
Stablecoin issuance and reserve arrangements
Both models involve risks, and neither should be assumed to have an unconditional government guarantee.
The central difference is that BUIDL combines an investment product with blockchain settlement, while conventional dollar stablecoins focus primarily on maintaining a redeemable digital dollar.
What Are the Benefits of Investing in BUIDL?
BUIDL offers several potential advantages, particularly for institutions that already hold substantial amounts of short-term dollar assets.
1. Income From Short-Term US Government Securities
The fund gives eligible investors exposure to Treasury bills and other short-term instruments without requiring them to manage each security individually.
These instruments generally carry lower credit risk than speculative cryptocurrencies, although they are not risk-free.
2. Around-the-Clock Token Transfers
BUIDL supports transfers between approved participants throughout the week, including weekends and holidays.
That could reduce operational delays compared with financial products whose transfers depend entirely on conventional market hours.
However, around-the-clock token transfers should not be confused with guaranteed instant cash redemptions.
3. Potentially More Efficient Settlement
Blockchain-based ownership records can support faster settlement and simplify certain transfer and reconciliation processes.
For institutions managing liquidity across several trading venues, this may reduce some of the operational friction associated with moving collateral.
4. Yield-Bearing Collateral
BUIDL can potentially allow an institution to earn investment income on assets used as collateral, subject to platform rules and risk controls.
This is increasingly important for crypto trading firms that otherwise may need to hold non-yielding collateral.
5. Greater Onchain Transparency
Token issuance and transfers can be observed on public blockchains, improving visibility into aspects of fund activity.
However, blockchain transparency does not mean every underlying investment, liability or operational detail is independently visible onchain.
What Are the Risks and Disadvantages of BUIDL?
Despite BlackRock’s involvement and its holdings of relatively conservative assets, BUIDL is not risk-free.
1. $1 Value Is Not Guaranteed
BlackRock’s original disclosure explicitly warns that the fund may not always maintain a $1 token value.
Losses can occur, and the product should not be treated as equivalent to insured bank deposits.
2. Limited Investor Access
The high minimum investment and qualified purchaser requirements exclude most retail investors.
That limits BUIDL’s usefulness for individuals seeking a simple alternative to a savings account or conventional money market fund.
Security failures or operational disruptions could interfere with access to tokens or transfers.
4. Liquidity and Redemption Restrictions
BUIDL tokens can be transferred only within the permitted investor framework.
Even with additional trading arrangements, finding a buyer or redeeming an investment may depend on available counterparties, fund procedures and market conditions.
5. Regulatory and Counterparty Risks
BUIDL depends on multiple financial and technology providers, including the fund manager, administrator, transfer agent, custodians and relevant trading platforms.
Regulatory changes, service disruptions or failures involving these parties could affect investors.
6. Interest Rate and Opportunity Costs
Returns may decline when short-term US interest rates fall.
Investors also face opportunity costs if other eligible cash-management products provide better returns, lower fees or more suitable liquidity terms.
The original fund disclosures warn that blockchain investments and private placements may expose investors to substantial losses, including loss of principal.
Why Are Binance, OKX and Other Crypto Exchanges Using BUIDL?
One of BUIDL’s most significant developments has been its transition from a tokenized investment product into an asset that institutions can use as trading collateral.
Traditionally, crypto traders have posted stablecoins, cash or other accepted assets as collateral for leveraged positions.
These holdings may earn little or no income while they remain committed to trading activity.
BUIDL offers a different approach: eligible institutions can potentially hold an income-generating Treasury fund while using its shares to support trading obligations.
Several developments illustrate this shift:
June 2025: Crypto.com and Deribit announced BUIDL collateral integrations.
November 2025: Binance began accepting BUIDL through an institutional off-exchange collateral arrangement.
February 2026: Securitize and Uniswap Labs introduced BUIDL trading through UniswapX for qualified, whitelisted participants.
April 2026: OKX, BlackRock and Standard Chartered announced a framework allowing eligible clients to use BUIDL as trading collateral, with custody arrangements involving Standard Chartered.
July 2026: BUIDL expanded to Tempo, extending its presence in blockchain-based payments and treasury infrastructure.
These arrangements could make tokenized Treasury products more useful for institutional capital management. However, using BUIDL as collateral also introduces additional exposure to margin requirements, liquidation rules, custody arrangements and the operational risks of participating trading venues.
How Does BUIDL Compare With Other Tokenized Treasury Funds?
BlackRock faces competition from both established asset managers and crypto-native companies.
Institutional tokenized fund with multiple collateral integrations
BENJI
Franklin Templeton
Tokenized fund ecosystem built around blockchain-recorded fund shares
USYC
Circle
Tokenized yield-bearing product used in institutional onchain finance
USDY
Ondo Finance
Tokenized yield product designed for eligible non-US investors
OUSG
Ondo Finance
Tokenized Treasury exposure for eligible investors
These products do not all have identical legal structures, investor eligibility requirements or redemption mechanisms.
BUIDL’s advantage lies partly in BlackRock’s asset-management infrastructure and the growing number of institutions integrating the fund.
However, competitors may offer different investment minimums, distribution arrangements, blockchain support or liquidity features.
The choice for eligible investors depends on more than the theoretical yield. Fees, legal rights, redemption procedures, collateral acceptance and operational reliability can be equally important.
What Does BUIDL Mean for the Future of Finance?
BUIDL illustrates a broader change in how financial assets may be issued, held and transferred.
Historically, a Treasury fund and a blockchain-based trading platform operated through largely separate infrastructure.
Tokenization creates opportunities to connect them.
An institution could hold shares in a Treasury fund, receive investment income and potentially use those shares in approved onchain financial transactions without relying on every conventional transfer process.
This does not eliminate the need for custodians, regulators, asset managers or other intermediaries.
In BUIDL’s case, those institutions remain central to the product.
The innovation is that some ownership and settlement functions can operate through blockchain infrastructure while the underlying investment remains tied to traditional financial markets.
BlackRock’s expansion into collateral services and DeFi-connected trading suggests that institutional adoption may increasingly depend on practical uses rather than token issuance alone.
Still, the long-term commercial impact remains uncertain. Tokenized funds must demonstrate that faster transfers, improved collateral mobility and new settlement options deliver measurable advantages over existing financial infrastructure.
Is BlackRock’s BUIDL Fund Worth Investing In?
BUIDL offers an example of how traditional investment products can operate on blockchain infrastructure without abandoning conventional asset management.
Its appeal is relatively straightforward: eligible institutions can gain exposure to short-term US dollar yields while benefiting from tokenized ownership, approved around-the-clock transfers and increasingly sophisticated collateral applications.
With approximately $2.17 billion in tokenized assets in October 2026, the fund has demonstrated meaningful institutional demand.
However, BUIDL remains inaccessible to most individual investors, and its tokenized structure introduces risks that do not disappear simply because BlackRock manages the portfolio.
For the broader market, BUIDL’s importance may ultimately depend less on how much money it attracts and more on whether tokenized fund shares become a practical part of everyday institutional trading, payments and settlement.
Disclaimer:
The information provided in this article is for informational purposes only. It is not intended to be, nor should it be construed as, financial advice. We do not make any warranties regarding the completeness, reliability, or accuracy of this information. All investments involve risk, and past performance does not guarantee future results. We recommend consulting a financial advisor before making any investment decisions.
Dr. Guneet Kaur is a senior editor at CCN.com and a Science Fellow at Exponential Science. She is a fintech and blockchain expert with extensive experience in digital finance education, blockchain ecosystems, and cryptocurrency markets. She has worked with global media such as Cointelegraph, as well as education and blockchain platforms, to design and lead strategic content and learning initiatives. As an educator and assessor for top-tier executive programs, she bridges real-world fintech trends with academic insight.
Dr. Kaur is also a published researcher and peer reviewer across fintech and data science journals, including Financial Innovation Journal and International Journal of Big Data Intelligence and Applications. Her work spans data-driven analysis, Web3 innovation, and technical content development. With a strong foundation in both industry and academia, she translates complex financial technologies into practical applications, empowering learners, professionals, and institutions across the rapidly evolving digital finance landscape.


 Intermediate








 Ripple’s RLUSD Scores Moody’s A2 Rating and Highest P-1 Short-Term Grade: What Investors Should Know